Fixed Indexed Annuities: How Principal Protection and Guaranteed Income Work
Fixed Indexed Annuities: How Principal Protection and Guaranteed Income Work
As you approach or enter retirement, your financial priorities shift dramatically. During your working years, the goal is accumulation, growing your portfolio as aggressively as possible. But in retirement, the strategy changes to preservation and income distribution. Learn how Cross Point approaches this on our annuities page. The fear of market volatility, economic downturns, and outliving your money becomes very real. For neutral product education, see Investor.gov on annuities.
Many retirees look for a financial solution that offers growth potential without exposing hard-earned savings to stock market crashes. This is where Fixed Indexed Annuities (FIAs) come in. At Cross Point Solutions, we work with individuals and business owners to help them understand how fixed indexed annuities function in plain, understandable English.
What Is a Fixed Indexed Annuity?
A Fixed Indexed Annuity is a contract issued by an insurance company. It combines the safety of a traditional fixed annuity with growth potential linked to a stock market index, such as the S&P 500 or Dow Jones Industrial Average.
Unlike investing directly in the stock market, your money is never actually invested in equities. Instead, the insurance company uses a portion of its fixed-income investments to credit interest to your annuity based on the underlying index's performance. If the market goes up, your annuity account earns interest up to specified caps or participation rates. If the market drops, your principal balance remains completely protected against loss.
The Core Mechanics: 0% Floor, Caps, and Participation Rates
To evaluate whether a Fixed Indexed Annuity fits into your retirement strategy, you need to understand three core contractual mechanisms: the 0% floor, caps, and participation rates.
1. The 0% Downside Market Floor
The most important feature of an FIA is the 0% floor guarantee. In years when the underlying market index loses value, your annuity returns 0% rather than taking a negative loss. Your previous gains and principal balance are locked in, ensuring market downturns never reduce your account balance.
2. Interest Caps
An interest cap represents the maximum percentage rate your annuity can earn during a specific crediting period. For example, if your FIA has a 9% annual cap and the S&P 500 gains 15%, your account is credited with 9%. In exchange for principal protection, you trade away unlimited upside gains.
3. Participation Rates
A participation rate determines what percentage of the index growth is credited to your contract. If your annuity has an 80% participation rate and the index gains 10%, your credited growth rate for that year would be 8%.
How an FIA Outperforms Volatility in Down Markets
To understand the power of locked-in gains, consider a side-by-side scenario comparing a $100,000 direct market investment with a $100,000 Fixed Indexed Annuity over a 3-year market cycle:
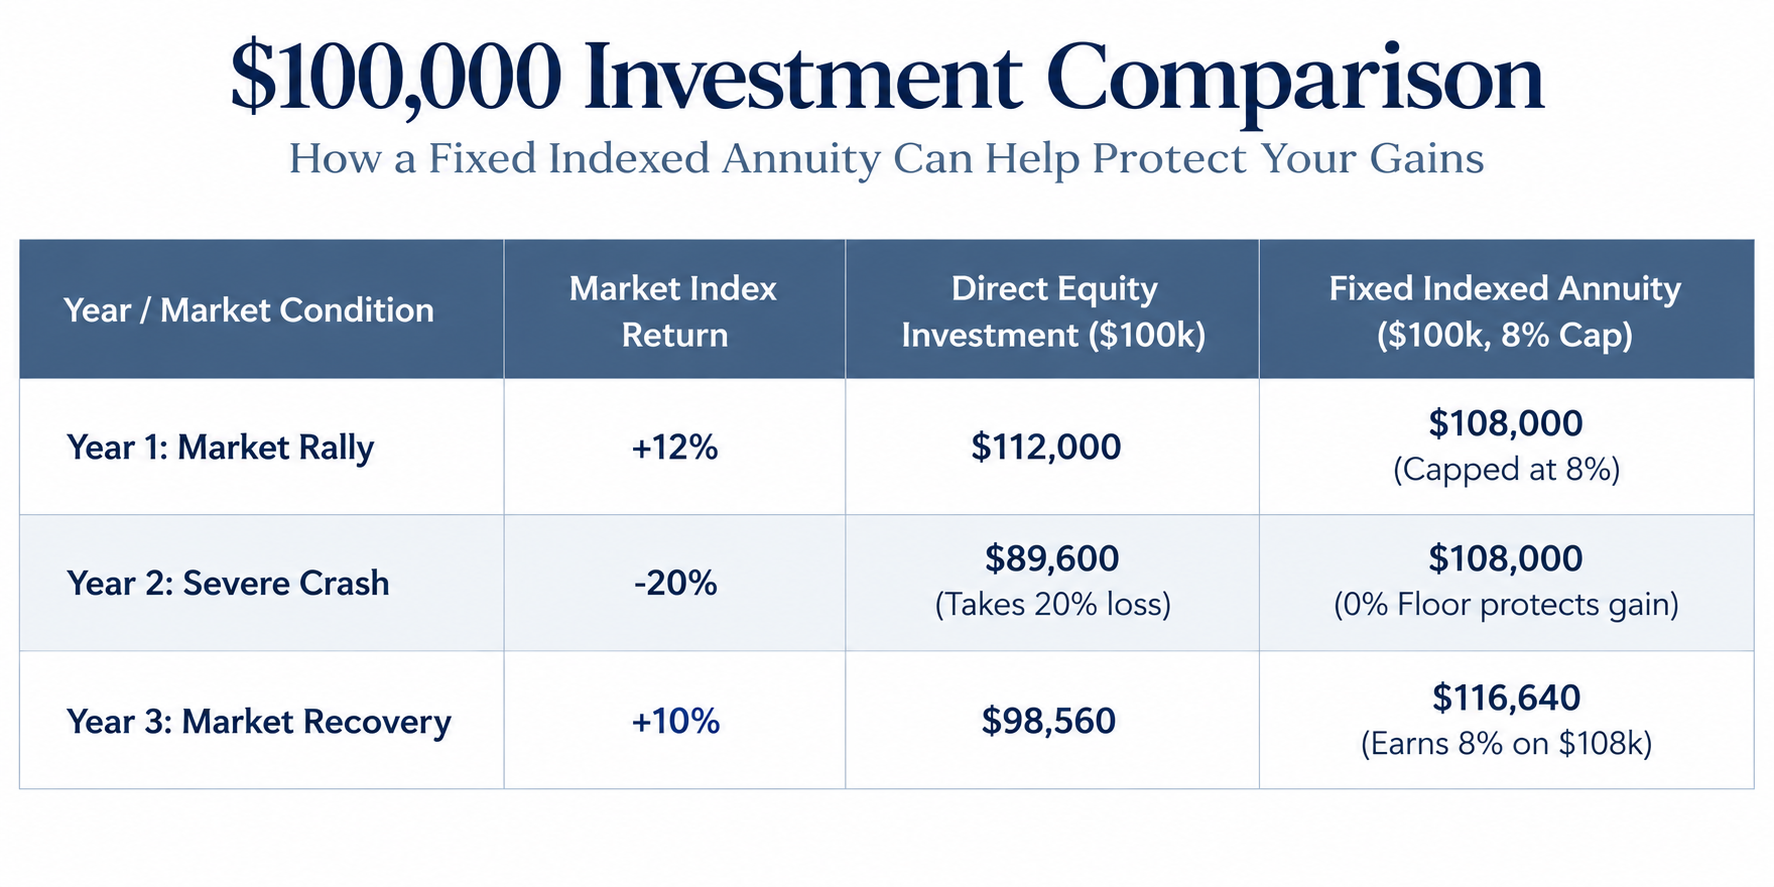
Notice how market loss recovery works. When a direct investment drops by 20%, it requires a 25% gain just to break even. Because the FIA never suffered a loss in Year 2, Year 3 growth built directly on top of previous gains. This resetting principle is known as the "annual reset mechanism."
Guaranteed Lifetime Income Riders (GLIR)
Beyond principal protection and growth, one of the most popular uses of a Fixed Indexed Annuity is creating a personal pension through a Guaranteed Lifetime Income Rider.
An income rider allows you to turn your annuity balance into a guaranteed stream of income that lasts for the rest of your life, regardless of how long you live or how market conditions perform. For retirees without a traditional pension, an FIA income rider provides a predictable income foundation that covers baseline living expenses alongside Social Security.
How Fixed Indexed Annuities Compare to Other Options
Understanding where FIAs sit relative to other financial vehicles helps clarify their role in your overall retirement plan
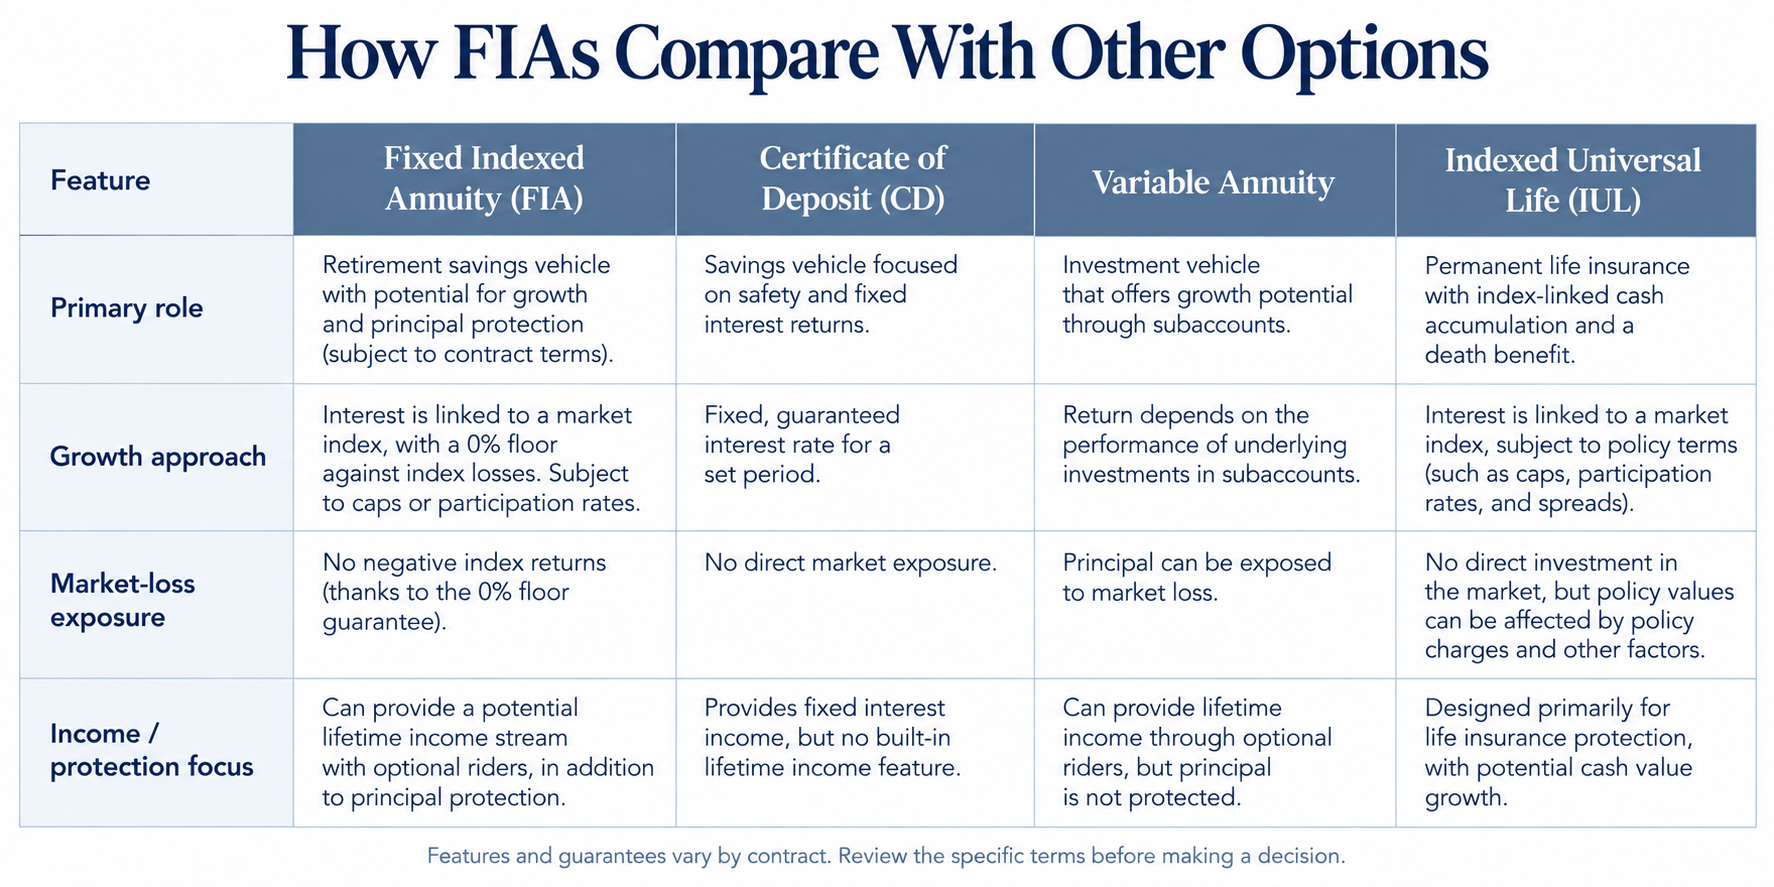
For entrepreneurs and independent business owners structuring their corporate retirement benefits, FIAs can also serve as a capital preservation tool. Explore our guide on Small Business Retirement Plans for additional business planning options.
How to Evaluate a Fixed Indexed Annuity Contract Before You Sign
Because Fixed Indexed Annuities vary widely between insurance carriers, taking a structured approach to evaluation ensures you select the contract that aligns with your specific financial goals.
When reviewing annuity proposals with your financial advisor or insurance professional, pay close attention to these critical contract elements:
• Crediting Methods: Ask whether the interest crediting is calculated on a Point-to-Point annual basis, Monthly Average, or Multi-Year basis. Point-to-Point crediting is popular because it compares the index value at the beginning of the contract year to the value on the exact anniversary date, simplifying returns.
• Carrier Financial Ratings: Since annuity guarantees are backed by the issuing insurance company, select carriers are rated A- or higher by independent rating agencies such as A.M. Best, Standard & Poor's, or Fitch. Strong financial strength ratings ensure long-term stability for lifetime income payouts.
• Bailout Provisions: Some FIA contracts include a bailout feature. If the insurance company drops the annual cap rate below a specified threshold in future years, you have the contractual right to surrender the contract without paying surrender charges.
• Rider Flexibility: Verify whether guaranteed lifetime income riders can be turned on or off when your personal cash flow needs change, or if income payments must begin immediately upon contract issue.
Who Benefits Most From a Fixed Indexed Annuity?
Fixed Indexed Annuities are not for everyone, and an honest evaluation of your goals is essential. An FIA may be a strong candidate if you:
• Are within 5 to 10 years of retirement or already retired.
• Want to protect a portion of your rollover IRA or 401(k) against stock market volatility.
• Desire a guaranteed lifetime income stream that you cannot outlive.
• Prefer moderate, steady growth over high-risk, speculative investing.
Understanding Liquidity, Surrender Charges, and Fees
Transparency is core to our philosophy at Cross Point Solutions. Fixed Indexed Annuities are long-term financial commitments, and understanding contractual guidelines prevents surprises later:
• 10% Free Withdrawals: Most FIA contracts allow you to withdraw up to 10% of your account value annually without penalty after the first year.
• Surrender Charge Periods: If you withdraw more than the free allowance during the contract period (typically 7 to 10 years), surrender charges apply. This is why you should only place money in an FIA that you do not need for short-term emergency liquidity.
• Fee Structure: Base Fixed Indexed Annuities frequently carry 0% annual contract fees. Optional riders, such as guaranteed income riders, typically cost between 0.95% and 1.25% annually.
To assess how much guaranteed income you need in retirement, download our free Retirement Readiness Checklist.
Plan Your Protection with Cross Point Solutions
Retirement planning should feel empowering, not stress-inducing. At Cross Point Solutions, we believe in education first and pressure never. We take the time to evaluate your existing retirement accounts, analyze your income gaps, and help you decide whether a Fixed Indexed Annuity belongs in your plan.
Ready to protect your savings and build guaranteed income for retirement? Schedule a complimentary consultation with Zina Smith today at our Cross Point Solutions Appointment Page.
Disclaimer: This article is provided for educational purposes only and does not constitute financial, tax, or legal advice. Annuity guarantees are backed by the financial strength and claims-paying ability of the issuing insurance carrier. Consult with a licensed insurance professional, CPA, or financial advisor regarding your personal financial circumstances.
When you are ready to see whether a fixed indexed annuity fits your income plan, book a free conversation: https://crosspointsolutions.net/appointment